Your paper invoice just stopped being a tax document in Nigeria.
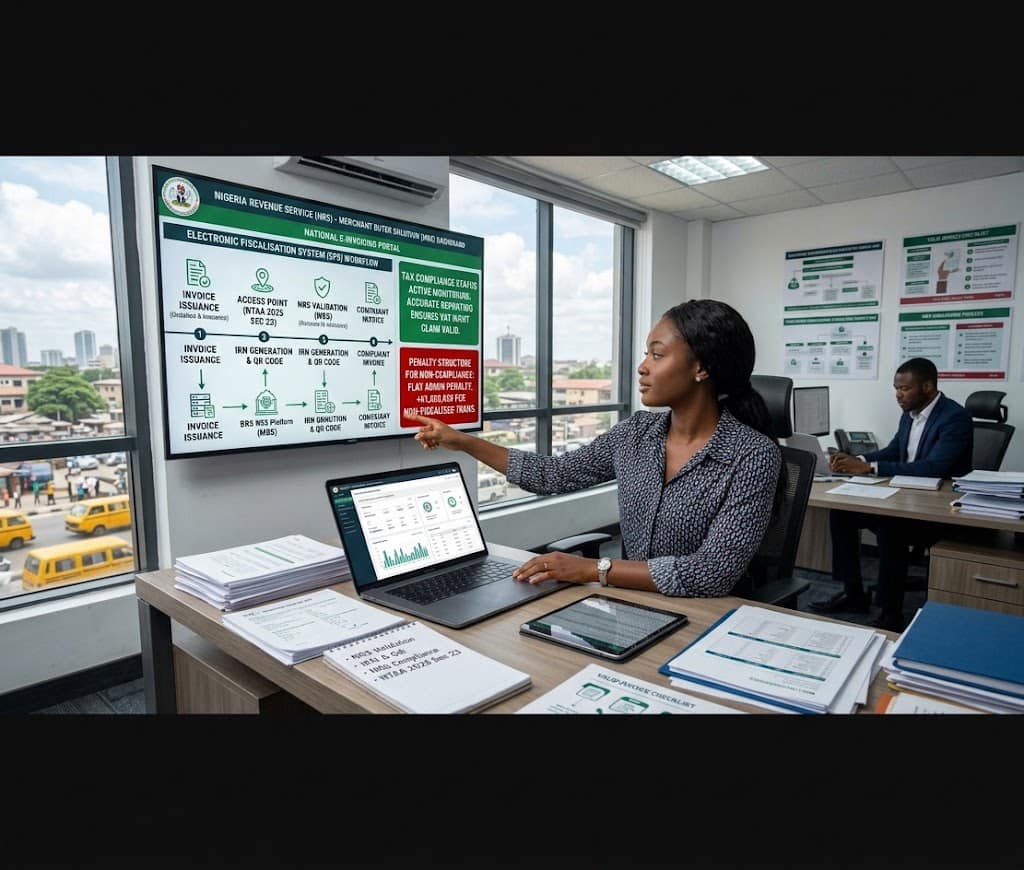
Nigeria’s tax reform didn’t just change rates and thresholds , it changed what counts as a valid invoice. Under section 23 of the Nigeria Tax Administration Act (NTAA), 2025 and section 158 of the Nigeria Tax Act (NTA), 2025, taxable supplies must now be recorded and reported through an approved Electronic Fiscal System (EFS). In practice, that means the National E-Invoicing regime run by the Nigeria Revenue Service (NRS) Merchant Buyer Solution (MBS).
Here’s what that looks like in practice, not just in theory.
Large taxpayers are already past their deadline — the NRS began active compliance monitoring after 31 July 2026. If your turnover sits between ₦1bn and ₦5bn, your go-live date has effectively arrived; treat it as live now rather than a future task.
How it actually works — a worked example
Banga Ltd (a large taxpayer) sells ₦20,000,000 worth of goods to Retail Co.
Before the mandate: Bangas accountant raises an invoice in Excel, emails a PDF to Retail Co. Job done , that PDF was good enough to support Retail Co’s input VAT claim.
Under the EFS: Bangas accounting system pushes the invoice through an accredited Access Point Provider to the NRS Merchant Buyer Solution. NRS validates it in real time and returns an Invoice Reference Number (IRN), a QR code, and a Cryptographic Stamp Identifier (CSID). Only an invoice carrying all three is a compliant, tax-effective document while the PDF alone no longer is.
The part that catches most businesses off guard
This isn’t only a filing obligation for the seller. Under the new framework, a buyer can only claim VAT input credit on invoices validated and transmitted through the MBS platform. If your supplier’s invoice was never fiscalised, that liability lands on you, the buyer, not just on them.
Worked example: the cost of an unvalidated invoice
Retail Co buys ₦20,000,000 of stock from Banga and pays 7.5% VAT — ₦1,500,000.
If Banga’s invoice carries a valid IRN: Retail Co books the full ₦1,500,000 as input VAT against its own VAT liability, as normal.
If Banga never transmitted the invoice through MBS: Retail Co has no valid input VAT claim on that ₦1,500,000 even though it paid the tax in good faith to a real supplier for a real transaction.
The practical fix: procurement and accounts payable teams now need to check for a valid IRN and QR code before an invoice is booked not just before it’s paid.
Worked example: what late onboarding actually costs
Tivbantu Manufacturing (a large taxpayer) misses its onboarding deadline by 10 days. Here is what stacks up in that window alone, before any underlying tax exposure is even counted:
• Day 1 of default: ₦1,000,000
• Days 2–10 (9 days) at ₦10,000/day: ₦90,000
• Flat administrative penalty: ₦200,000
• Plus 100% of the tax due on every non-compliant transaction issued in that window
Ten days of delay: ₦1,290,000 in penalties alone — and that’s before the tax on the actual transactions is added ba ck.
What to actually do about it
• Confirm your taxpayer band and go-live date. Don’t assume “small business” protects you indefinitely. The emerging-taxpayer date is 1 July 2027, and enforcement follows from January 2028.
• Onboard onto NRS MBS ahead of your deadline, not on it. Large taxpayers who waited are the ones now facing active compliance monitoring.
• Pick an accredited Access Point Provider and integrate it with your ERP or accounting system. This is a systems project, not a form-filling exercise.
• Reboot your accounts-payable checklist. No valid IRN and QR code on a supplier invoice means no automatic input VAT claim, flag it before you book it, not after an audit finds it.
• Push compliance upstream to your suppliers as appropriate. A non-compliant supplier is now a cash-flow risk to you, so make MBS-validated invoicing a condition in new and renewed contracts.
The bottom line
E-invoicing in Nigeria has moved from a pilot to an enforcement reality for large taxpayers, with medium taxpayers effectively live and small taxpayers on a clear runway. The businesses that will feel the least pain are the ones treating the Invoice Reference Number the way they already treat a TIN, as something you check before you rely on the document in the first place, not after the fact.
This article is for general information and does not constitute tax advice. Verify your specific taxpayer classification, onboarding deadline, and Access Point Provider requirements directly with the Nigeria Revenue Service.
Sources: Nigeria Tax Administration Act, 2025 (section 23); Nigeria Tax Act, 2025 (section 157); NRS public notices on the National E-Invoicing and Electronic Fiscal System (EFS) / Merchant Buyer Solution (MBS), 2025–2026.
#NigeriaTax #E- Invoicing #NRS #TaxCompliance #NTAA2025 #VAT #DigitalTax #TaxConsulting #VASP


About Post Author
